Term loan
A lump sum for a one-time need such as expansion or a new outlet, repaid in EMIs over an agreed tenure.
Last updated:
See how business loans work, what lenders usually evaluate, and submit an enquiry to discuss your funding requirement.
Enquire about Business Loan
Thanks for sharing your details. Our team will review your requirement and connect with you shortly.
A business loan gives your business funds for a specific need, such as buying stock or machinery, opening a new outlet, hiring, marketing or meeting working capital gaps. You repay it in EMIs over an agreed tenure.
Business loans can be unsecured, based on the strength of your business and credit history, or secured against property, machinery or other assets. Lenders look at how long the business has run, its turnover, cash flow, tax filings and existing debt before deciding the amount, rate and tenure.
Each lender sets its own criteria. In short, it wants to see a business that earns steadily and an owner who has repaid past credit on time. Commonly reviewed factors are:
Lenders ask for KYC, business proof and financial records. The exact list depends on the lender, the constitution of your business and the amount you request.
The lender assesses your business as well as you. For an unsecured loan, the usual sequence is below; a secured loan adds a legal and valuation check on the asset.
You share how much you need, what it is for and the tenure you want, along with basic business details.
The lender collects KYC, business proof, bank statements, tax returns and financial statements.
The lender reviews cash flow, turnover, existing debt and the credit reports of the business and its owners.
If approved, you receive the amount, rate, tenure and charges with a Key Fact Statement (KFS) showing the APR. Compare it with other offers before you accept.
You sign the agreement and complete any security or guarantee formalities, after checking the terms match the sanction letter.
The lender transfers the funds to the business bank account, or pays the supplier for machinery or equipment, and EMIs start as agreed.
Banks and NBFCs regulated by the RBI must give you a Key Fact Statement, including the annual percentage rate (APR) and repayment schedule, before you sign a retail or MSME term loan agreement. Source: RBI circular on Key Facts Statement, 15 April 2024.
Enter a loan amount, the interest rate from your offer and a tenure to see the monthly EMI and total interest, then check it against your monthly cash flow.
Example only, not an offer
Reducing-balance calculation. It excludes fees and charges. Open the full EMI calculator
An unsecured business loan does not need you to pledge property or other assets. The lender decides mainly on your business's cash flow, tax filings and credit history, so it suits businesses that need funds quickly without tying up an asset.
A secured business loan is backed by property, machinery, deposits or other assets. Because the lender has security, it may offer a different amount, tenure or rate. The risk is that the lender can act on the asset if the loan is not repaid.
Some lenders extend collateral-free credit to eligible micro and small enterprises under government credit guarantee schemes such as CGTMSE. Whether your loan qualifies depends on the lender and the scheme's rules.
Business funding comes in different forms for different needs. What is available, and on what terms, depends on the lender and your business.
A lump sum for a one-time need such as expansion or a new outlet, repaid in EMIs over an agreed tenure.
Funds for day-to-day needs such as stock, salaries and supplier payments, usually for a shorter tenure.
To buy machinery or equipment, often secured by the equipment being purchased.
Collateral-free credit for eligible micro and small enterprises, covered by schemes such as CGTMSE where the lender participates.
A secured loan against residential or commercial property you own, often used for larger amounts.
Funds against unpaid invoices from your customers, repaid when the customer pays.
Two offers with the same rate can cost very different amounts. When you compare:
Estimate your EMI and total interest with the EMI calculator
The interest rate is only part of the cost. Charges differ by lender, so check each of these in writing:
Charged for evaluating your application, and often deducted from the amount disbursed.
What you pay to repay early, where the lender is allowed to charge.
Penalties if an EMI is missed or paid late.
Tax added to the processing fee and other charges.
Including valuation if security is offered.
Where a credit guarantee scheme covers the loan, the lender may pass on its fee. Ask how it is charged.
For floating-rate business loans to individuals and micro and small enterprises sanctioned or renewed on or after 1 January 2026, many regulated lenders cannot charge for prepayment; for some lender types this applies up to a sanctioned amount of ₹50 lakh. Source: RBI (Pre-payment Charges on Loans) Directions, 2 July 2025.
| Business loan | Business overdraft | Loan against property | |
|---|---|---|---|
| How funds are given | A one-time lump sum | A limit you draw from when needed | A lump sum after the property is checked |
| How interest is charged | On the outstanding balance, built into EMIs | Generally only on the amount used, for the days it is used | On the outstanding balance, built into EMIs |
| Security | Unsecured or secured | Unsecured or secured, depending on the lender | A residential or commercial property you own |
| Best for | One-time investments such as expansion or machinery | Uneven or seasonal working capital needs | Larger needs where you can mortgage a property |
| Repayment | Fixed EMIs over an agreed tenure | Repay and reuse within the limit; renewed as per lender terms | EMIs over an agreed tenure |
Swipe the table sideways to see all three options.
Rates, limits and charges differ by lender and by your business profile, so compare actual offers rather than product types alone.
Lenders do not always share the exact reason. Common ones include:
Before you reapply, file your returns on time, keep business transactions in the business account, check the credit reports of the business and its owners, and reduce existing debt where you can. A smaller amount or a secured option may also be easier to approve.
Fraudulent loan offers often target small businesses. Protect yourself:
Borrow only from RBI-regulated banks and NBFCs. If you are unsure about a lender, check that it is a bank or an NBFC registered with the RBI.
Check that the lender's name on the sanction letter and agreement matches the lender you applied to, including when you apply through an app or an agent.
Never pay an upfront fee to "get a loan approved". Genuine fees are disclosed in writing by the lender.
Do not share OTPs, PINs, passwords or card details with anyone who calls or messages you about a loan.
Read the loan agreement fully before you sign, and keep a copy of every document you sign.
Be careful with offers that promise approval regardless of your documents or credit history.
Business loans are commonly used for expansion, buying stock or machinery, opening a new outlet, marketing, hiring and working capital. Lenders may ask about the purpose and may restrict some uses.
Not always. Many lenders offer unsecured business loans based on cash flow, tax filings and credit history. Larger amounts may need security, and some collateral-free loans to micro and small enterprises are covered by government credit guarantee schemes.
Business vintage, turnover, profitability, banking behaviour, GST and income tax filings, existing debt, and the credit history of the business and its owners.
Some lenders lend to relatively new businesses, but a longer operating history, regular tax filings and steady bank credits usually make approval easier. Criteria differ by lender.
Usually KYC of the owners, business proof such as GST or Udyam registration, income tax returns, financial statements and business bank statements. Partnerships and companies also submit the partnership deed or incorporation documents.
A business loan is paid out once and repaid in fixed EMIs. A business overdraft is a limit you can draw from, repay and draw again, with interest generally charged only on the amount used.
CGTMSE is the Credit Guarantee Fund Trust for Micro and Small Enterprises, which provides guarantee cover to lenders on eligible collateral-free credit to micro and small enterprises. Whether your loan is covered depends on the lender and the scheme's rules.
It is not always mandatory, but many lenders accept Udyam registration as business proof, and it is generally needed to benefit from schemes meant for micro, small and medium enterprises.
Lenders generally allow it. For floating-rate business loans to individuals and micro and small enterprises sanctioned or renewed on or after 1 January 2026, many regulated lenders cannot charge for prepayment; for some lender types this applies up to a sanctioned amount of ₹50 lakh. Check your sanction letter for the terms that apply.
Common reasons include a short business history, low turnover, weak banking behaviour, missing tax filings, a low credit score for the business or its owners, or high existing debt.
29 Oct 2026
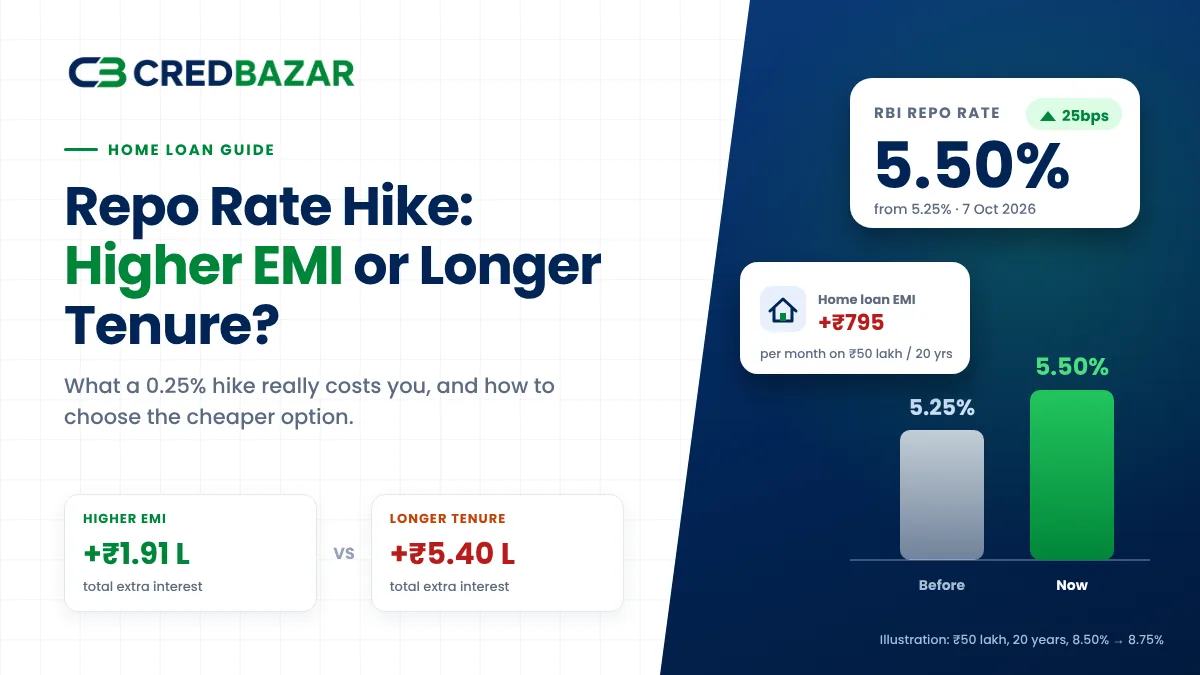
RBI has raised the repo rate to 5.50%. See how the hike affects your home loan or LAP, what a higher EMI or a...
29 Oct 2026
Earning well but still getting rejected? You are not alone. From the "Settled" CIBIL nightmare to negative pin...
09 Oct 2026
Thinking of taking a payday loan to survive until your next salary? Before you download that instant loan app,...
Fill in the short form on this page with your basic details and loan requirement.
The CredBazar team gets in touch to understand your requirement and explain the next steps.
Share the documents the lender asks for. Approval and final terms are decided by the lender.
About CredBazar. CredBazar helps you connect with lenders for your loan requirement. CredBazar is not the lender: whether your loan is approved, and the interest rate and terms you are offered, are decided by the lender.
The information on this page is general guidance and is not an offer of credit. Loan approval, interest rates, fees, tenure and other terms are decided by the lender and depend on your profile. Please read the lender's terms before you proceed.
Submit a short enquiry and the CredBazar team will get in touch with you.