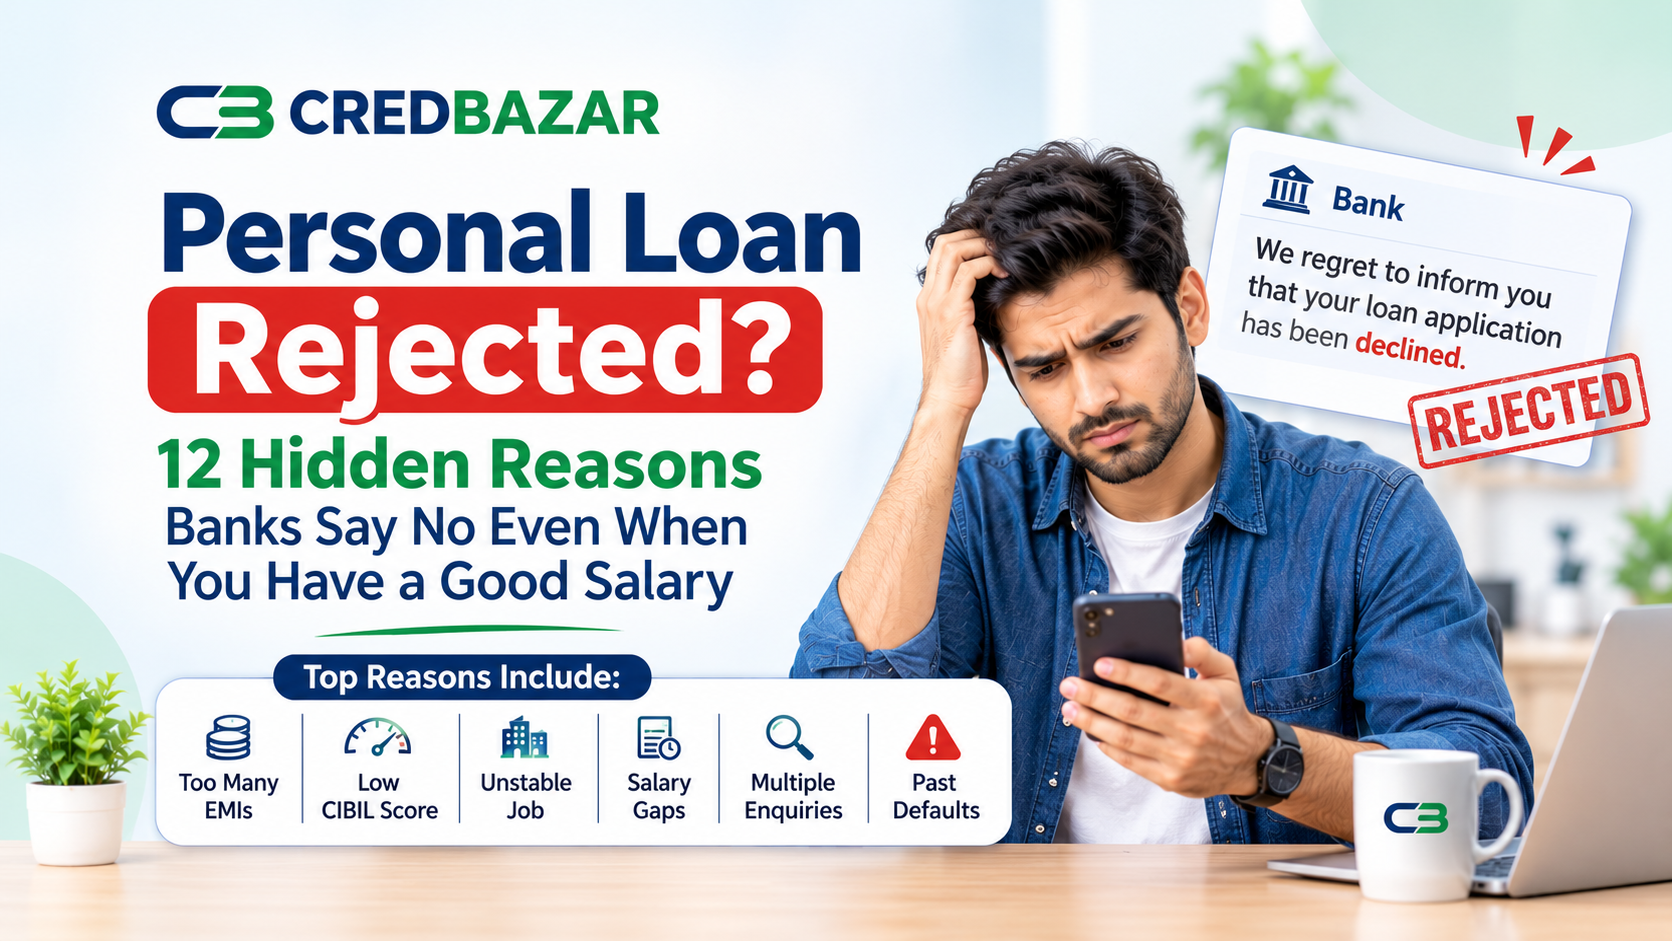
Personal Loan Rejected? 12 Hidden Reasons Banks Say No Even When You Have a Good Salary
You earn ₹80,000 a month. Your CIBIL score is decent. You have been at the same company for three years. You apply for a ₹3 Lakh personal loan for a family emergency.
And the next morning, you get an SMS: "We regret to inform you that your application has been declined."
You stare at your phone, frustrated. Why? I have the money. I can pay the EMI!
As a Senior Financial Consultant at CredBazar, I talk to people like you every single day. And honestly? It’s frustrating. Banks don’t always reject you because you are a "bad customer." They reject you because you don't fit their hidden checklist.
Here are the 12 real reasons banks say no, even when your salary looks perfectly fine.
1. The "Existing EMI" Trap & Too Many Loans
Banks don't care about how much you earn. They care about how much of your salary is left over after paying your current debts.
Let’s say your take-home salary is ₹80,000. But you are already paying ₹25,000 for a car loan and ₹15,000 for a credit card EMI. That’s ₹40,000 gone. Most banks in India will not give you a new loan if your existing monthly EMIs eat up more than 60% to 70% of your take-home salary.
Also, if you already have more than 3 personal loans running in your CIBIL report, many banks and NBFCs will outright reject you. Even if you are paying them on time, they think you are stuck in a debt cycle and surviving on borrowed money.
CredBazar Tip: Close your small "Buy Now Pay Later" (BNPL) schemes and old credit card EMIs before applying to free up your monthly salary.
2. The "Settled" Nightmare & The Same-Bank Rule
So your CIBIL score is 750. That’s good, right? Not necessarily. Banks look at the details, not just the score.
If you settled a credit card or a consumer loan years ago, your report will show a "Settled" or "Written-Off" status. This is a massive red flag. But here is the biggest catch: If you settled a loan with Bank A, Bank A will almost never approve a new loan for you. They have a long memory, and their internal system will block you, even if your current CIBIL score is perfect.
CredBazar Tip: Download your free CIBIL report. If you see a "Settled" tag, pay off the remaining amount and ask the lender to update it to "Closed." Never settle a loan unless you have zero options.
3. They Check How You Use Credit, Not Just the Score
Banks don't just look at the number; they look at your repayment behavior across different products.
If you are paying your Home Loan perfectly on time, but you constantly default or delay your Personal Loan or Credit Card payments, it's a huge issue. Banks see this as a sign that you only pay when there is a property involved, but you are careless with unsecured debt. They will assume you will do the same to them.
CredBazar Tip: Being a guarantor for a friend's loan? If they default, it hits your CIBIL report too. Never be a guarantor unless you are ready to pay that loan yourself.
4. You Work for a "Category C" or Unstable Company
Banks categorize companies. If you work for a small startup or a local firm, a bank might reject you—even if your salary is ₹1 Lakh.
Specifically, banks and NBFCs are very scared of funding employees from real estate agencies, manpower agencies, or companies that are less than 1 year old. They think these companies could shut down tomorrow or lay off staff overnight. They have zero loyalty to your income; they only trust the company's stability.
CredBazar Tip: If you work for a startup or a new agency, apply through an aggregator like CredBazar. We know which banks are startup-friendly and which ones will reject you based on your company's name.
5. Job Hopping (The 3-Month Rule)
Banks love stability. They usually want to see at least 3 months in your current job. If you have changed three jobs in the last two years, the system will flag you as a "high risk." They want to know you will stick around long enough to pay the EMIs.
CredBazar Tip: If you just joined a new company and haven't completed 3 months, don't lose hope. A few NBFCs can process your application based on your offer letter and previous salary slips. You just need to apply with the right lender.
6. The "Desperation" Signal: Too Many Enquiries
You need money fast. So you open an app and apply to HDFC. Rejected? Apply to ICICI. Rejected? Try Bajaj.
Every time you click "Apply," the bank does a "hard enquiry" on your report. If a bank sees that 5 different lenders checked your report in the last 15 days, they will assume you are in deep trouble and reject you instantly.
CredBazar Tip: Stop applying everywhere. Let an expert at CredBazar check your eligibility without hitting your CIBIL score.
🛑 Hit a roadblock already? Stop applying blindly.
Every time you hit "Apply" on a random app, your CIBIL score drops. Don't ruin your chances further. Let the experts at CredBazar check your profile for free. We'll tell you exactly which bank will say "Yes" to you.
📲 WhatsApp Us Now for a Free Eligibility Check - No CIBIL Impact
7. Weird Salary Modes, Gaps, and Delays
Banks want to see a clean, predictable salary credit.
Salary Mode: If your salary comes via cash, cheque, or even IMPS, many banks will reject your application. They want to see a standard NEFT/NACH corporate credit.
Salary Gaps: If you get your salary on the 1st of one month and the 20th of the next, the bank thinks your company is facing a cash crunch.
Weak Average Balance: If you withdraw 100% of your salary on day one and leave the account at zero, banks think you have no savings or financial discipline.
CredBazar Tip: Keep your salary account clean. Don't let your balance drop to zero immediately.
8. Gambling and Shady Transactions
Your bank statement tells a story. If the bank sees regular transactions linked to gambling apps, betting, or risky crypto platforms, they will reject you. They assume your money is not safe and you might blow the loan amount on speculative activities.
CredBazar Tip: Use a separate bank account for your small online transactions, but keep your salary account strictly for bills, rent, and savings.
9. Profile Mismatch: Business Intent or PG Resident
This is a silent killer.
Business Intent: If you apply as a "Salaried" employee, but you have a registered business in your name, banks will get suspicious. They assume you will use the personal loan for your business, which is against RBI rules for personal loans. Using a personal loan to invest in the stock market is also a strict no.
PG Residents: If you live in a Paying Guest (PG) accommodation, a few banks will reject you. Why? Because it's hard to verify your address and track you down if you run away with the money.
CredBazar Tip: Always be honest about your residence and employment type. Let an expert match you with a lender that accepts your profile.
10. Location Matters: The "Negative Area" Rule
Here is something no one tells you. Every bank has a list of "Negative Pin Codes" or "Negative Areas."
If you live or work in an area that the bank has flagged due to high loan defaults or severe collection issues, they will reject your application. It doesn't matter if you are a perfect customer; the bank's system simply won't allow funding in that specific location.
CredBazar Tip: Don't take it personally. Just apply through a platform like CredBazar. We know which banks fund in your specific area.
11. You Are Too Close to Retirement
Most personal loans have a tenure of up to 5 years. If you are 56, the bank will realize you might retire before the loan is fully repaid. Unless you have a co-applicant or a massive pension plan, they will say no.
CredBazar Tip: If you are above 55, consider taking a joint loan with your son or daughter. It instantly boosts your approval chances.
12. The Permanent Blacklist: Fraud History
This is the one mistake that can ruin your financial life for years.
Let's say you really needed a loan, but your salary slips weren't enough. So, you gave manipulated or fake documents to Bank A. They caught you, rejected the loan, and flagged your PAN card.
Banks and NBFCs share data through central fraud repositories. If you get flagged at one bank, other banks will also reject you for the exact same reason. You can have a perfect salary and a high CIBIL score, but if there is a "fraud" tag on your PAN, no lender will touch you.
CredBazar Tip: Never submit fake documents. Getting blacklisted is just not worth it.
The Real Issue: You Applied to the Wrong Bank
Here is the honest truth. Not all banks have the same rules.
A private bank might reject you because half your salary is going towards old EMIs. But an NBFC might approve you in 10 minutes. A bank might reject you because you live in a PG or work for a new company. But a digital-first lender might love your profile.
The problem is you don't know the rules of each bank. And when you apply randomly, you just damage your CIBIL score.
What Should You Do Now?
If you just got rejected, don't panic. And please, don't apply to another bank immediately.
Ask for the reason: The bank's email or SMS usually has a specific reason. Read it carefully.
Check your CIBIL report: Look for old unpaid bills, "Settled" tags, or incorrect information.
Talk to an expert: This is where CredBazar comes in.
At CredBazar, we don't just push your application to a random bank. We look at your profile—your salary, your monthly expenses, your company's category, and even your pin code—and we match you with the banks that actually want to give you money. We have PAN India partnerships with top banks and NBFCs.
Stop guessing. Let us find your perfect lender.
Whether you have a low CIBIL score, a new job, or a complicated profile, we have a partner bank that will understand your situation. No hidden fees, no fake promises. Just honest financial advice.
👇 Choose how you want to get started:
💬 WhatsApp Us: Message "LOAN" to 7827290918 on WhatsApp for a free profile check in 5 minutes. Click here to chat directly
🌐 Check Eligibility Online: Click here to fill out our 2-minute form on CredBazar. Zero impact on your CIBIL score.
📞 Talk to an Expert: Call us at 7827290918 (Mon-Sat, 10 AM to 7 PM).
Let's get you that loan—tension-free.