Home loan
To buy, build or renovate a home. The home is mortgaged to the lender until the loan is repaid.
Last updated:
Understand how secured loans work, the common types, and what to check before pledging an asset. Submit an enquiry to discuss your options.
Enquire about Secured Loan
Thanks for sharing your details. Our team will review your requirement and connect with you shortly.
A secured loan is a loan backed by an asset you pledge as security, such as a property, a vehicle, gold, a fixed deposit or investments. If the loan is not repaid as agreed, the lender can use that asset to recover its dues, subject to the agreement and the law.
Because the lender has security, it looks at the value of the asset as well as your income and credit history. That is why secured loans can differ from unsecured loans in the amount, tenure and rate offered. The trade-off is that you put the asset at risk, so borrow only what you can comfortably repay.
A lender checks you and the asset. Criteria differ by lender and product; commonly reviewed factors are:
Along with your KYC and income documents, you need papers for the asset. The exact list depends on the product and lender.
The steps depend on the asset. A gold or deposit-backed loan can be quick, while a property-backed loan adds legal and valuation checks. The usual sequence is:
Pick the product that matches your goal and the asset you have: home loan, loan against property, vehicle loan, gold loan or another option.
You submit KYC, income documents and the papers for the asset you are offering.
The lender verifies ownership and title and values the asset. The amount it lends depends on this value.
If approved, you receive the amount, rate, tenure and charges with a Key Fact Statement (KFS) showing the APR. Compare it with other offers before you accept.
You sign the agreement, and the lender's charge is created on the asset, for example a mortgage on property or hypothecation of a vehicle.
The loan is paid out. When you repay in full, the lender releases the asset and its documents and removes its charge.
Banks and NBFCs regulated by the RBI must give you a Key Fact Statement, including the annual percentage rate (APR) and repayment schedule, before you sign a retail or MSME term loan agreement. Source: RBI circular on Key Facts Statement, 15 April 2024.
For home loans and other loans the RBI classes as personal loans, regulated banks and NBFCs must return your original property documents and remove any charge registered on the property within 30 days of full repayment or settlement, and compensate you for delays caused by them. Source: RBI circular on release of property documents, 13 September 2023.
Enter a loan amount, the interest rate from your offer and a tenure to see the monthly EMI and the total interest you would pay.
Example only, not an offer
Reducing-balance calculation. It excludes fees and charges. Open the full EMI calculator
With an unsecured loan, such as most personal loans, you do not pledge anything. The lender decides mainly on your credit history and income.
With a secured loan, the asset gives the lender another way to recover its money. That is why lenders can offer different amounts, tenures or rates on secured products. The amount usually depends on the value of the asset, and the lender keeps a charge on it until you repay.
Either way, missed payments are reported to credit bureaus and lower your credit score. With a secured loan, you can also lose the asset.
The right secured loan depends on what you need the money for and what asset you have. Availability and terms depend on the lender.
To buy, build or renovate a home. The home is mortgaged to the lender until the loan is repaid.
Funds for business or personal needs against a residential or commercial property you already own.
To buy a car, two-wheeler or commercial vehicle. The vehicle is hypothecated to the lender.
A loan against gold jewellery or coins, which the lender holds until you repay.
A loan or overdraft against your deposit, usually with the same lender. The deposit keeps earning interest.
A loan against shares, mutual funds, bonds or insurance policies the lender accepts.
When you are pledging an asset, compare carefully:
Estimate your EMI and total interest with the EMI calculator
Secured loans often carry charges linked to the asset. Charges differ by lender, so check each of these in writing:
Charged for assessing your application.
For valuing the asset and checking its title.
On the mortgage or other security documents, as per your state.
What you pay to close the loan early, if the lender is allowed to charge.
Penalties if an EMI is missed or paid late.
Any fee for releasing the asset or documents. Ask about these before you sign.
For floating-rate loans to individuals for non-business purposes, sanctioned or renewed on or after 1 January 2026, regulated lenders cannot charge for prepayment. Source: RBI (Pre-payment Charges on Loans) Directions, 2 July 2025.
| Home loan | Loan against property | Vehicle loan | Gold loan | |
|---|---|---|---|---|
| Security | The home being financed | A property you already own | The vehicle being financed | Gold jewellery or coins |
| Use of funds | Buying, building or renovating a home | Business or personal needs, as the lender allows | Buying the vehicle | Most legitimate needs, as the lender allows |
| Who holds the asset | You live in the home; the lender holds a mortgage | You keep using the property; the lender holds a mortgage | You use the vehicle; the lender is noted on the RC | The lender holds the gold until you repay |
| Typical tenure | Long | Medium to long | Short to medium | Usually short |
| Process | Checks on you and the property | Checks on you and the property | Checks on you and the vehicle | Gold tested and valued at the branch |
Swipe the table sideways to see all four options.
Amounts, rates and charges differ by lender, by your profile and by the asset, so compare actual offers rather than product types alone.
A secured loan can be declined because of you or because of the asset. Common reasons include:
Before you reapply, get the asset's papers in order, check your credit report and correct any errors, and reduce existing dues where you can. A smaller amount or a different asset may also be easier to approve.
You are putting an asset at risk. Protect yourself:
Borrow only from RBI-regulated banks and NBFCs. If you are unsure about a lender, check that it is a bank or an NBFC registered with the RBI.
Check that the lender's name on the sanction letter and agreement matches the lender you applied to, including when you apply through an app or an agent.
Never pay an upfront fee to "get a loan approved". Genuine fees are disclosed in writing by the lender.
Do not share OTPs, PINs, passwords or card details with anyone who calls or messages you about a loan.
Read the loan agreement fully before you sign, and keep a copy of every document you sign.
Keep copies of every asset document you hand over, and get a written receipt listing them.
A secured loan is backed by an asset you pledge, such as property, a vehicle, gold, a fixed deposit or investments. If the loan is not repaid as agreed, the lender can use the asset to recover its dues, subject to the agreement and the law.
A secured loan is backed by an asset the lender can use to recover dues. An unsecured loan, such as most personal loans, has no such asset, so the lender relies mainly on your credit history and income.
Because the lender has security, secured loans can offer different amounts, tenures or rates compared with unsecured loans, depending on the lender and the asset. They also suit purposes such as buying a home or vehicle.
Common examples are residential or commercial property, vehicles, gold, fixed deposits, and investments such as shares, mutual funds or insurance policies. Each lender decides which assets it accepts.
It depends on the asset's value as assessed by the lender, the lender's policy for that asset type, and your income and credit profile. The lender confirms the amount in the sanction letter.
It depends on the product. You keep living in a mortgaged home and using a hypothecated vehicle, while gold and some deposits are held by the lender until you repay.
You may pay late charges, your credit score can fall, and if dues stay unpaid the lender can act on the asset as per the agreement and the law. Talk to the lender early if you expect difficulty.
After you repay the loan in full. For home loans and other loans the RBI classes as personal loans, banks and NBFCs regulated by the RBI must return the original property documents and remove any charge registered on the property within 30 days of full repayment or settlement.
Yes. A home loan is secured by the property being bought or built, which is mortgaged to the lender until the loan is repaid. Loans against property and vehicle loans are also secured loans.
Common reasons include unclear title or missing approvals for the asset, a valuation lower than expected, a low credit score, income that is too low for the EMI, or co-owners not joining the loan.
29 Oct 2026
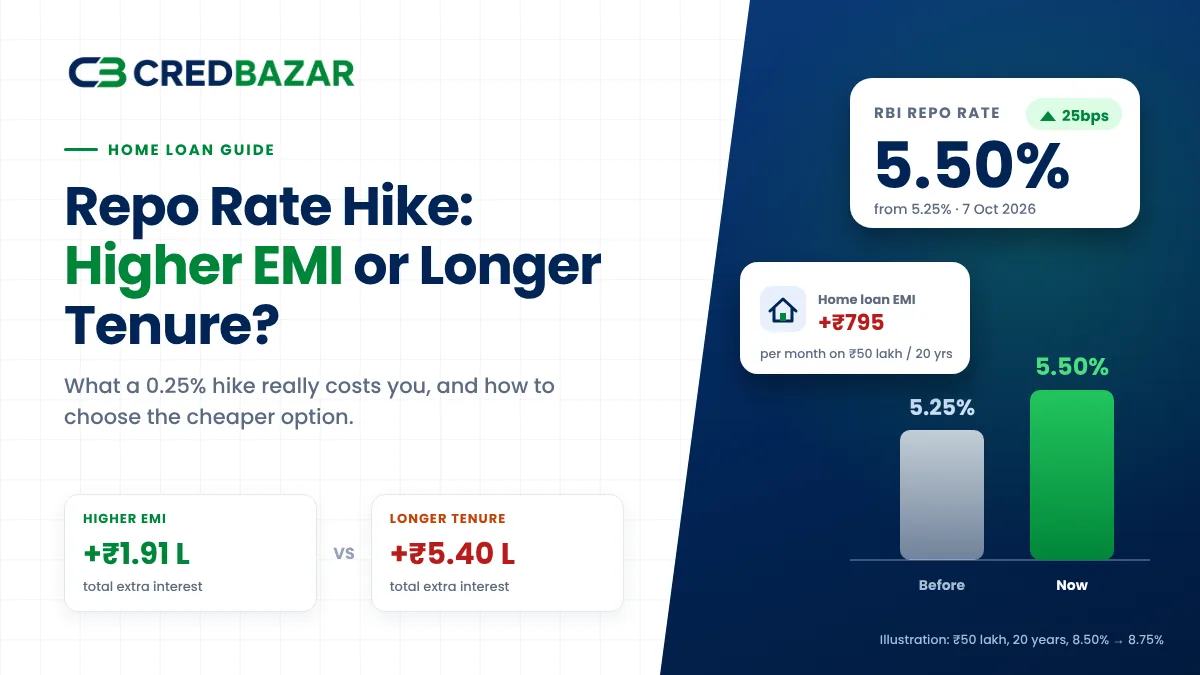
RBI has raised the repo rate to 5.50%. See how the hike affects your home loan or LAP, what a higher EMI or a...
29 Oct 2026
Earning well but still getting rejected? You are not alone. From the "Settled" CIBIL nightmare to negative pin...
09 Oct 2026
Thinking of taking a payday loan to survive until your next salary? Before you download that instant loan app,...
Fill in the short form on this page with your basic details and loan requirement.
The CredBazar team gets in touch to understand your requirement and explain the next steps.
Share the documents the lender asks for. Approval and final terms are decided by the lender.
About CredBazar. CredBazar helps you connect with lenders for your loan requirement. CredBazar is not the lender: whether your loan is approved, and the interest rate and terms you are offered, are decided by the lender.
The information on this page is general guidance and is not an offer of credit. Loan approval, interest rates, fees, tenure and other terms are decided by the lender and depend on your profile. Please read the lender's terms before you proceed.
Submit a short enquiry and the CredBazar team will get in touch with you.