One of our loan borrowers mahadev patil ji he is from pune told us that he had to admit his mother at midnight and as we all know the hospital needed the payment upfront ( in his case 1.50 lakh). And as most salaried people he did not have sufficient savings at that time (₹40,000 in savings). What did he do?.
Let's be honest — emergencies never come with a warning. And when they hit, the last thing you want is confusion about money.
Why does this confusion happen?
Both give you quick funds.
Both feel similar when you're stressed.
But they are very different in cost.
Let's break it down simply.
Interest Rate: This Is Where It Gets Real
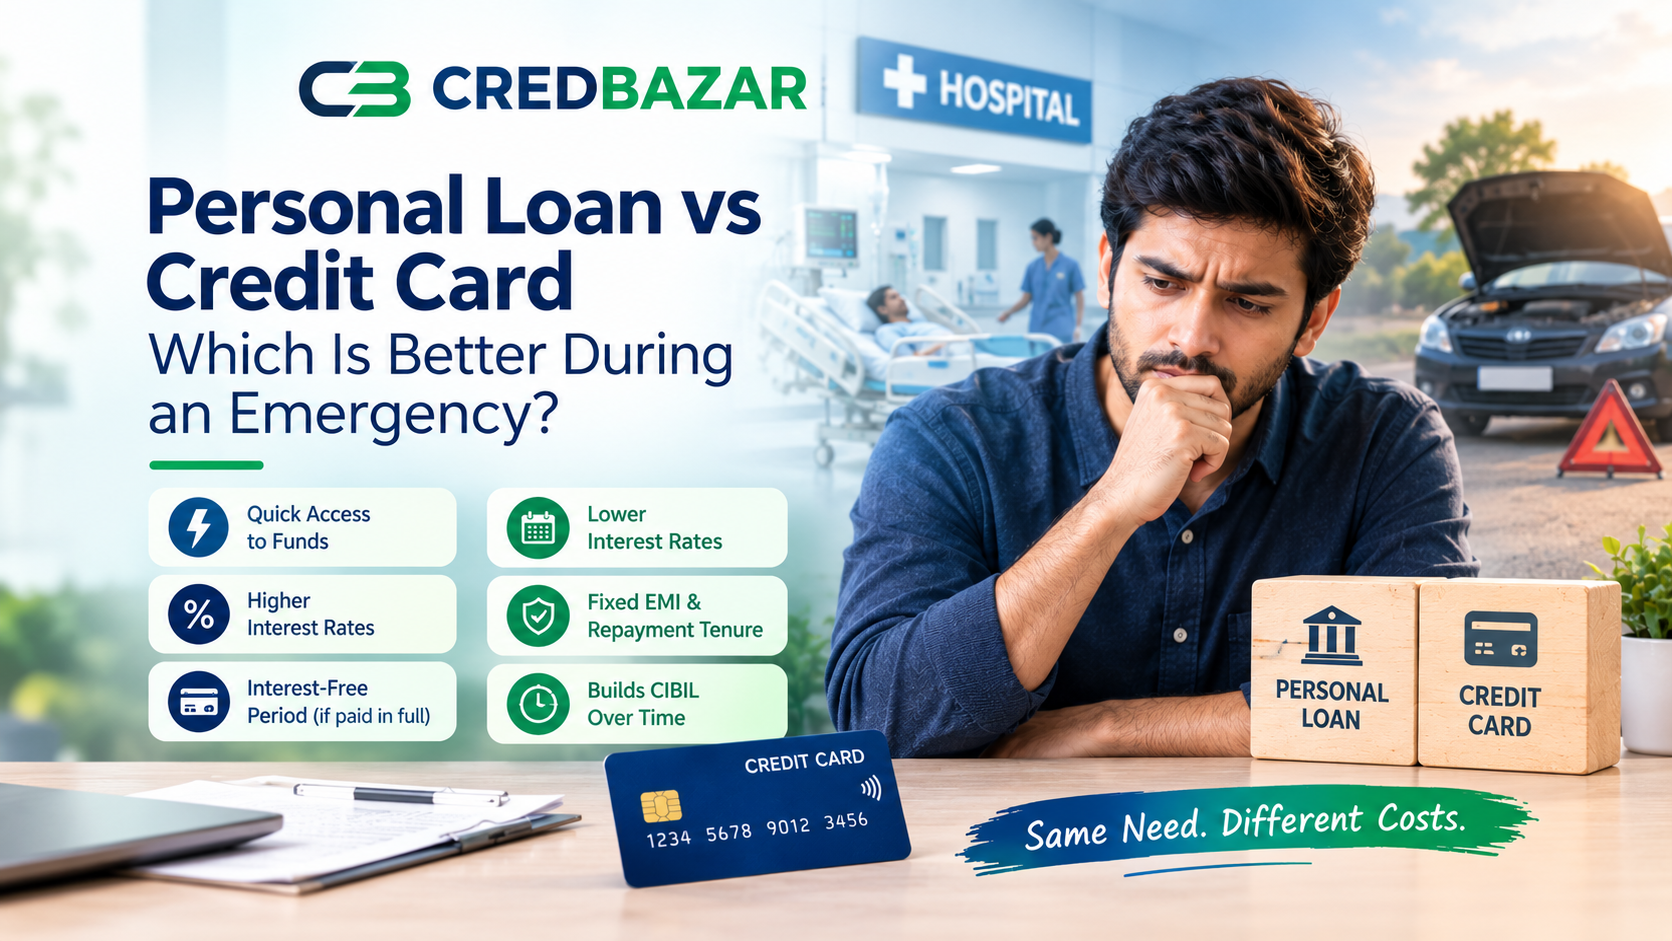
Personal Loan: 9.95%–18% per year. Axis Bank starts at 9.75%, HDFC and ICICI from 9.99%.
Credit Card (unpaid balance): 36%–42% per year. Yes, you read that right.
On a ₹1 Lakh emergency repaid over 12 months:
Personal Loan interest: ~₹6,000–₹10,000.
Credit Card interest: ₹40,000+.
Grace Period & EMI
Credit Card: You get 30-45 days interest-free if you pay in full. Miss that, and interest starts from day one.
Personal Loan: No grace period. EMI starts from the next month. But the rate is fixed and predictable.
CIBIL Impact
Credit Card: High usage (above 30% of your limit) hurts your CIBIL score. It makes you look "credit-hungry".
Personal Loan: A new loan lowers your score slightly at first. But paying EMIs on time improves your CIBIL score.
Hidden Charges — Watch Out
Personal Loan: Processing fee 0.5%–5% of loan amount. HDFC charges up to ₹6,500 + GST. SBI up to 1.5%. From 2026 onwards most of the banks in India offer zero pre-closure/foreclosure charges of loan amount more than 10 lakh
Credit Card: Cash advance fee 2.5%–3% (min ₹500). Late payment fee ₹100–₹1,300 depending on outstanding. Over-limit fees now need your explicit consent.
Approval Speed
Credit Card: Instant. Swipe or withdraw at ATM. No approval needed.
Personal Loan: A few hours to 2 days for disbursal after approval.
Loan Amount
Credit Card: Limited by your credit limit. Usually ₹25,000–₹5 Lakhs.
Personal Loan: ₹50,000 to ₹40 Lakhs depending on your salary, current organization and CIBIL.
Now let's see how this plays out in real situations.
5 Emergency Scenarios
1. Medical Emergency
Hospital bill of ₹2 Lakhs. You have 3 months to repay.
Verdict: Personal Loan. Credit card interest will kill you.
CredBazar Tip: Many hospitals accept credit cards for the bill. But if you can't pay in full by the due date, convert it to a personal loan immediately.
( In case of mahadev patil he paid all bill from his credit card and once credit card statement generated he took loan and paid credit card bill on due date )
2. Car Breakdown
Repair cost ₹15,000. You can repay next month.
Verdict: Credit Card. Pay in full by due date. Zero interest.
CredBazar Tip: Use a card that gives rewards on fuel or auto services. You get cashback AND interest-free credit.
[tips for salaried always carry credit card that gives surcharge waiver on petrol pump ]
3. Job Loss
No income for 3 months. Need ₹1 Lakh for household expenses.
Verdict: Personal Loan. But apply before you lose the job. Once unemployed, approval becomes very tough as they need latest salary slip to process application.
CredBazar Tip: If you already have a personal loan, talk to your bank about restructuring. RBI guidelines allow it.
[tips : as a salaried person always have emergency savings of 6 times of net salary]
4. Travel Emergency
Family emergency in another city. Need ₹30,000 for flights and hotel.
Verdict: Credit Card for booking. If you can repay in 45 days, it's free. Otherwise, personal loan.
CredBazar Tip: Book flights with a credit card that gives travel insurance. Double benefit.
[As a salaried employee most of us leave our parents or city for work and lot of credit card in india will give you free airport lounge access and rewards as well make sure to have one ]
5. Home Repair
Roof leakage during monsoon. Cost ₹80,000. Contractor wants payment in 2 weeks.
Verdict: Personal Loan. You'll get time to repay over 12–24 months.
CredBazar Tip: Get 2–3 quotes first. Don't borrow more than needed. Processing fees add up.
[contact us we will suggest which bank will offer best option for your profile]
The Verdict
Use a credit card when:
The expense is small (under ₹20,000).
You can pay the full balance by the due date.
You need money right now.
Use a personal loan when:
The expense is large (₹50,000+).
You need 6–24 months to repay.
You want fixed EMIs and lower interest.
Never carry a credit card balance for months. That 36%–42% interest is a debt trap.
["In my 10 years of experience i have seen most of my friends get trapped just because of this mistake, always pay 100% of your billed amount on due date ]
One Last Thing
If you're not sure which option suits your situation, talk to us. We compare offers from 30+ banks and NBFCs. No paperwork. No tension.
Your CIBIL stays safe. Your wallet stays happy.