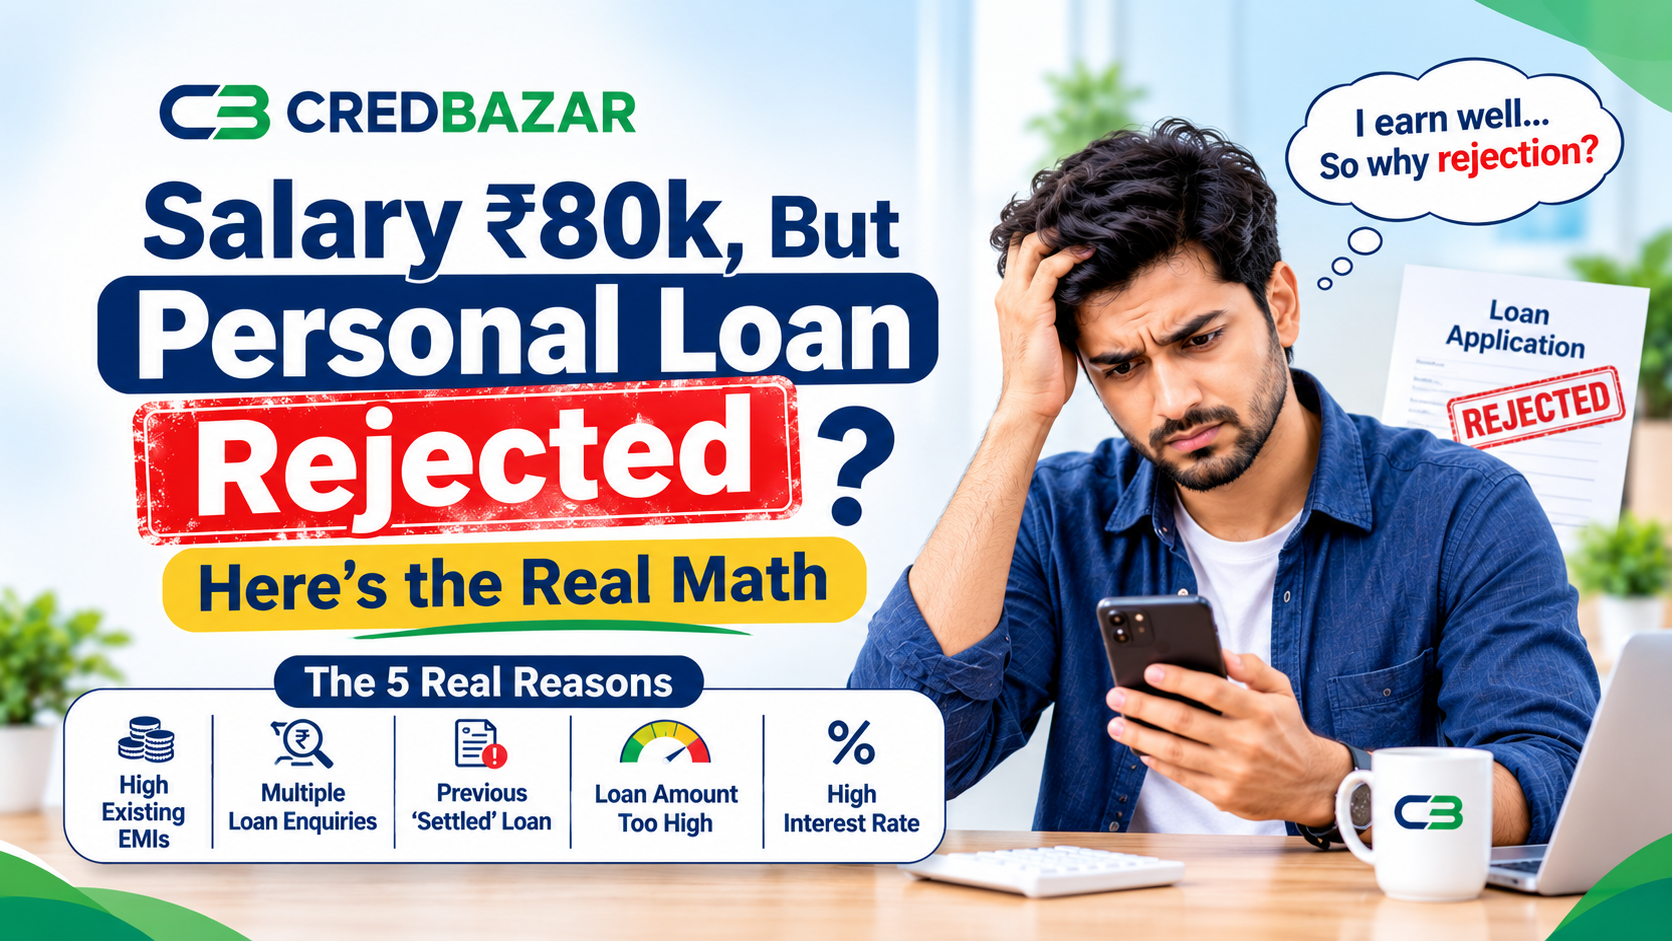
Salary ₹80k, But Personal Loan Rejected in Bangalore? Here’s the Real Math
You live in Bangalore. You earn a decent ₹80,000 a month. You need a personal loan of ₹5 Lakhs for a medical emergency or a family function back home.
You download an app, upload your salary slips, and hit "Apply."
Ten minutes later: "Sorry, your application has been declined."
Or even worse, you get approved, but the app offers you a loan at a ridiculous 24% interest rate. You sit there wondering, "I earn well, my company is an MNC, so why is this happening to me?"
As a Senior Financial Consultant at CredBazar, I speak to salaried folks in Bangalore every day. The problem isn't your salary. The problem is that banks run a completely different math in the background.
Let’s break down why this happens, and how you can fix it.
The 5 Real Reasons Your Loan Gets Rejected (Even on a Good Salary)
Before we get to the solutions, you need to understand why the system is saying no.
1. Your Existing EMIs are Eating Your Salary
Banks look at your FOIR (Fixed Obligation to Income Ratio). In simple words, they check how much of your monthly salary is already blocked by other loans.
Let's say your take-home is ₹80,000. You pay ₹18,000 for a car loan, ₹5,000 for a credit card EMI, and ₹3,000 for an iPhone on Amazon Pay Later. That’s ₹26,000 gone. If you add Bangalore rent (₹20,000), you are left with very little. Banks assume you won't be able to pay a new EMI.
2. Multiple Loan Enquiries in a Short Period
You needed money fast. So you applied to HDFC, ICICI, Axis, and Bajaj within three days.
Every time you click "Apply," the bank does a "hard enquiry" on your CIBIL report. If a lender sees 4 enquiries in 7 days, they assume you are desperate and in deep financial trouble. They will reject you instantly.
3. Previous Loan "Settled" Instead of "Closed"
Years ago, you had an argument with a bank over a ₹10,000 credit card bill and paid a settlement amount. It’s over, right? No. Your CIBIL report still shows a "Settled" status. For a bank, "Settled" means you didn't pay the full amount. It is a massive red flag, and most banks will reject you based on this single tag.
4. Required Loan Amount is Higher Than Eligibility
You want ₹10 Lakhs, but based on your salary and existing EMIs, the bank's system calculates your maximum eligibility at ₹4.5 Lakhs. If you apply for the higher amount, the system will auto-reject you without a human even looking at your file.
5. Approved at a High Interest Rate
If you have a slightly lower CIBIL score (around 700-720) or your profile is "high risk" due to your company's category, banks might approve you. But they will charge a higher risk premium (like 18% instead of 11%). Fintech apps are notorious for this.
5 Actionable Steps to Fix Your Eligibility
Here is exactly how you fix this, specific to the Indian banking system.
Step 1: Clear Small EMIs to Lower Your Debt Load
Banks usually don't let your total EMIs (including the new one) cross 50% to 60% of your take-home salary.
Look at your CIBIL report and your bank statement. Close those small "Buy Now Pay Later" (BNPL) accounts and short-term consumer loans.
Why it works: It instantly frees up your monthly cash flow and makes your profile look healthy to the underwriting system.
CredBazar Tip: Before applying, check if you have a "Pay Later" account active on Flipkart or Amazon. These are technically consumer loans and they reduce your personal loan eligibility. Clear them off completely.
Step 2: Stop the "App-Spree" and Wait
If you’ve already applied to 3-4 lenders and got rejected, stop right now. Every new application drops your CIBIL score by 5-10 points.
Wait for at least 3 to 6 months before applying again. Let the "hard enquiries" fade from your CIBIL report.
Why it works: It gives your credit profile time to heal and shows future lenders that you aren't desperately hopping from bank to bank.
CredBazar Tip: Never use random loan aggregator apps that check your CIBIL score directly. Always use a platform where an expert checks your profile eligibility first without touching your CIBIL. At CredBazar, we do soft checks to save your score.
Step 3: Fix the "Settled" Status on CIBIL
If you have a "Settled" or "Written-Off" tag on your credit report from a previous loan or credit card, you need to fix it before applying for a new loan.
Contact the old lender and ask them for a settlement amount. Pay it off and request an NOC (No Objection Certificate). Then, formally request them to update your CIBIL status from "Settled" to "Closed."
Why it works: A "Closed" status means the account is clear. Banks will still ask questions, but they won't auto-reject you like they do for "Settled" accounts.
CredBazar Tip: Under RBI guidelines, you are entitled to one free full credit report from every credit bureau (like CIBIL, Experian) every year. Pull your report and check for errors.
Step 4: Ask for the Right Amount (Do the Math)
Don't guess your eligibility. Let's do the real math for a Bangalore techie earning ₹80,000.
Assume your existing EMIs are ₹10,000. Banks usually allow a total EMI of up to 50% of your in-hand salary.
50% of ₹80,000 = ₹40,000 max total EMI allowed.
Minus existing EMIs (₹10,000) = ₹30,000 maximum new EMI possible.
If you take a personal loan at 13% for 3 years (36 months), an EMI of ₹30,000 roughly qualifies for a loan of ₹8.8 Lakhs.
If you ask for ₹10 Lakhs, you will be rejected.
Here is a quick look at how EMIs work for a 3-year loan at 13% interest:
| Loan Amount | Monthly EMI (Approx) | Total Interest Paid |
|---|---|---|
| ₹3,00,000 | ₹10,110 | ₹64,000 |
| ₹5,00,000 | ₹16,850 | ₹1,06,600 |
| ₹8,00,000 | ₹26,960 | ₹1,70,500 |
Why it works: By calculating your actual eligibility using tools like the CredBazar EMI Calculator, you apply for an amount the bank wants to give you.
CredBazar Tip: If your required loan amount is higher than your eligibility, consider adding a co-applicant (like your spouse or father) who has a good salary. Their income gets added to yours, instantly boosting your eligibility.
Step 5: Negotiate or Change the Lender Category
If a bank approves you at 18% interest, don't just accept it in a panic.
Banks categorize risk. A public sector bank (like SBI) might reject you for a small formatting error, while an NBFC (like Bajaj or Tata Capital) might approve you instantly but at a slightly higher rate.
Also, under RBI's Fair Practices Code, you have the right to negotiate the processing fee.
Why it works: Different lenders have different risk appetites. What is rejected by a traditional bank might be instantly approved by an NBFC at a reasonable rate.
CredBazar Tip: Do not just look at the interest rate; look at the APR (Annual Percentage Rate). A bank offering 11% interest with a 3% processing fee might actually be more expensive than a lender offering 12% with zero processing fees.
The Bottom Line: You Don't Have to Do This Alone
Getting a loan rejected when you are already stressed about money is a terrible feeling. But remember, it's rarely because you are bad with money. It's usually just a mismatch between your profile and the bank's hidden rules.
At CredBazar, we work with over 50+ top banks and NBFCs across India. We don't just push your application to a random bank.
We look at your salary, your existing EMIs, your company's category, and your CIBIL report, and we match you with a lender who will actually say "Yes" at a fair interest rate.
Still confused about why your loan was rejected? Or need a loan that actually gets approved?
Stop applying blindly. Your CIBIL score is too precious for that.
Let's get you that loan—tension-free.
💬 WhatsApp Us: Message "LOAN" to 7827290918 for a free profile check in 5 minutes. Click here to chat directly
🌐 Check Eligibility Online: Click here to fill out our 2-minute form on CredBazar. Zero impact on your CIBIL score.
📞 Talk to an Expert: Call us at 7827290918 (Mon-Sat, 10 AM to 7 PM).